
Defensive Stocks Drop to 2% Valuation Discount Against Cyclicals as DSP Mutual Fund Flags Two-Decade Extreme
Published: 2026-10-08 15:27 IST | Category: Markets | By Flash Finance desk (written with AI assistance) · Editor: Kokila
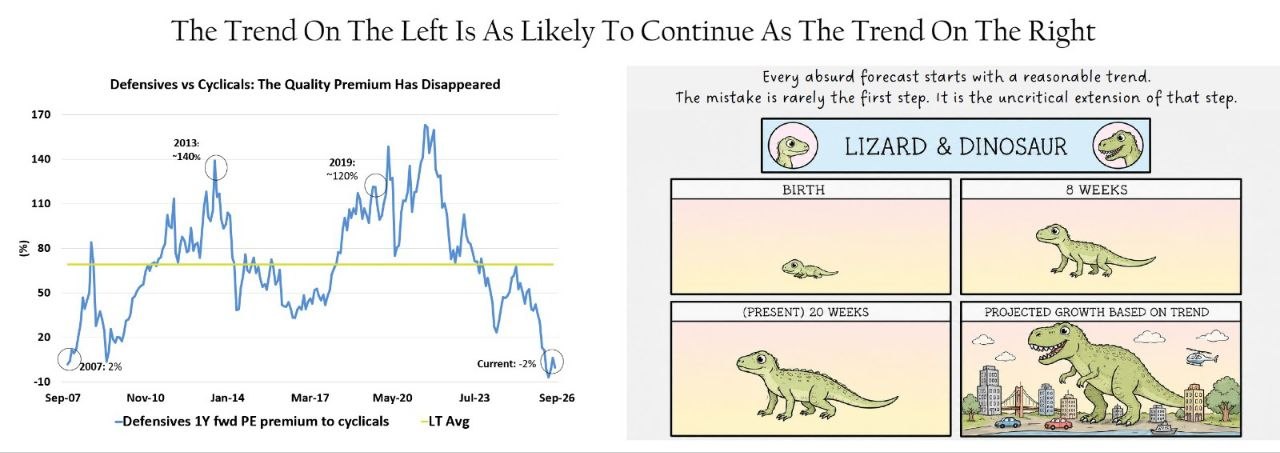
Indian equity markets are witnessing a valuation distortion not seen in nearly two decades. According to an analysis by Sahil Kapoor, Head of Products and Market Strategist at DSP Mutual Fund, defensive sectors have suffered one of their steepest relative deratings in modern market history. High-quality defensive franchises—primarily across information technology (IT), private sector banks, and fast-moving consumer goods (FMCG)—now trade at roughly the same forward valuation multiples as cyclical businesses, completely wiping out their historical premium.
According to data compiled by DSP Mutual Fund and Nuvama Research, the one-year forward Price-to-Earnings (P/E) premium of defensives over cyclicals has fallen to -2%, sinking well below its long-term average of approximately 70%. The last time the valuation premium collapsed to such an extreme was in 2007, near the peak of India's historic capital expenditure and infrastructure boom, when the premium stood at just 2%.
The Disappearing Quality Premium
Historically, Indian markets have rewarded defensive businesses with substantial valuation premiums owing to their predictable cash flows, high return on equity (RoE), and superior capital efficiency.
The historical trajectory of the defensive-to-cyclical valuation premium reveals cyclical extremes:
- 2007 Capex Boom: The premium compressed to 2%, as frenzy around infrastructure, metals, and real estate dominated investor appetite.
- 2013 Taper Tantrum Era: The defensive premium surged to around 140%, as investors sought shelter in consumer staples and software exporters amidst rupee volatility and macro headwinds.
- 2019 Pre-Pandemic Flight to Safety: The premium spiked again to roughly 120% during the aftermath of the NBFC credit crisis, concentrating liquidity into a handful of "quality compounders".
- Current Period: The premium has turned negative to -2%, reflecting complete parity between high-margin defensive compounders and cyclical companies.
Anatomy of the Cyclical Rally: Margins vs Revenues
A critical element of DSP's thesis lies in dissecting the composition of cyclical earnings. Kapoor noted that much of the earnings superiority exhibited by cyclical pockets—such as industrials, capital goods, power, metals, and public sector undertakings—has stemmed from sharp margin expansion rather than a structural, persistent divergence in revenue growth.
Across multiple cyclical sectors, operating margins and profitability ratios are currently hovering at or well above their long-term cyclical averages. Meanwhile, defensives have continued to deliver consistent underlying business performance, even as market prices experienced prolonged time corrections and relative deratings.
The market is therefore confronting an unusually demanding question: Have cyclical sectors undergone a permanent structural transformation that makes them as valuable as high-quality defensives, or are investors aggressively capitalizing peak-cycle economics far too far into the future?
The "Lizard & Dinosaur" Trap
To illustrate the psychological pitfall currently gripping market participants, Kapoor paired the valuation metrics with an allegorical comic titled "Lizard & Dinosaur," underscoring that "every absurd forecast starts with a reasonable trend. The mistake is rarely the first step. It is the uncritical extension of that step."
In market terms, while cyclical earnings recovery was grounded in legitimate demand pickup and balance sheet deleveraging over the initial phase of the cycle, extrapolating these peak margins indefinitely into the future assumes that a modest cyclical recovery will compound forever into a corporate giant. Historically, cyclical margins and earnings rarely remain at peak levels indefinitely, as capacity additions, input price variations, and competitive intensity inevitably enforce mean reversion.
Key Strategic Implications for Indian Investors
The compression of the quality premium presents distinct portfolio considerations for domestic wealth managers and retail investors:
Valuation Comfort in Large-Cap Defensives: Large-cap private lenders, IT majors, and staples now offer some of the most reasonable valuations seen since the global financial crisis or the 2020 pandemic trough. With their RoE profiles remaining structurally sound, downside risks appear comparatively buffered.
Margin Vulnerability in Cyclicals: Any cyclical deceleration in government infrastructure spending, global commodity demand, or elevated raw material costs could expose the vulnerability of cyclical earnings multiples priced to perfection.
Rebalancing Towards Quality: Historical market cycles demonstrate that when valuation spreads between defensives and cyclicals hit zero or negative territory, subsequent 3- to 5-year rolling returns heavily favor mean-reverting quality assets. Investors running portfolios heavily skewed toward recent cyclical winners may find this an opportune time to rebalance toward neglected quality leaders.
Tags: DSP Mutual Fund Sahil Kapoor Nifty 50 IT Sector Private Banks FMCG
